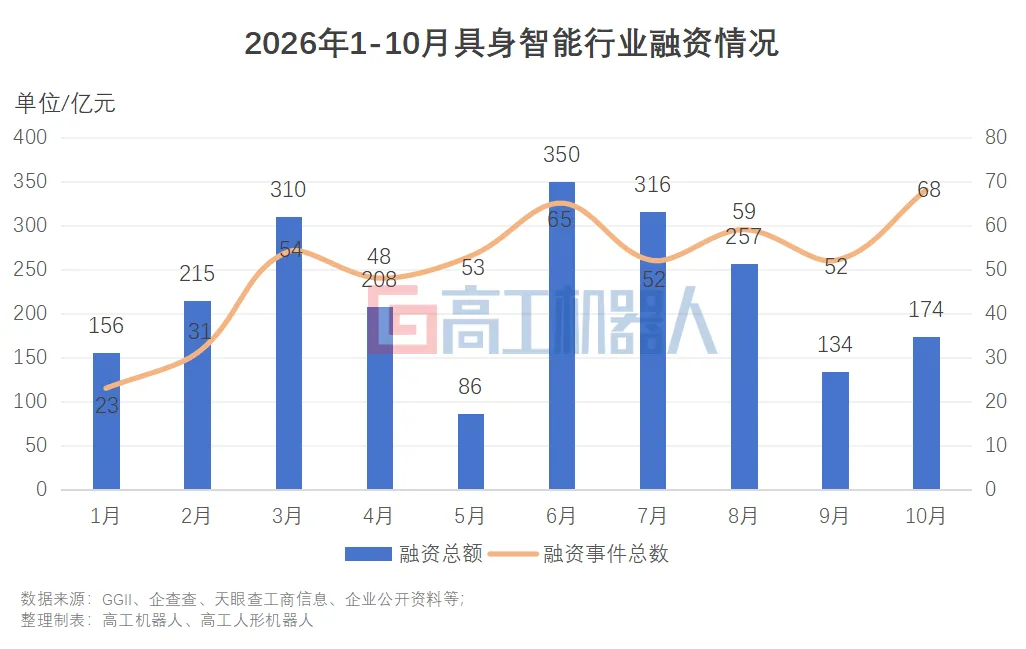
In September of this year, the high-tech industry seems to have set itself the test of a cliff-like downturn in the heat of venture capital financing.
The key question of the industry's cooling down is summed up in one sentence:Is there a real need for artificial intelligence to make money?
High-tech robots learn from the perspective of many experts that there are enough deployable scenarios with physical intelligence, that the space for collaboration in enterprises is much larger than the competition, and that making money is not difficult.
For example, Startup CEO Jay-Z has publicly stated that having physical intelligence is an industry that is very easy to make money from, and it is not as difficult as everyone says.
Li Tianwei, the co-founder of StarHealth, said that the opportunities for physical intelligence are large enough, that the boom in the first-tier market is not enough to scare companies away, and that the industry will focus on how to solve production problems in the second half of the year.
Chen Zhongqing, co-founder of Shijiazhuang, said that there are several billion tonnes of unicorns in the industry, but the current valuation is more the presentation of phased capabilities. The future core is whether the enterprise can open the deployment of the scenario, whether the model has a stable 24-hour performance capacity, whether commercialization is sustainable.
The smart co-founder, Suzanne, believes that the story of being physically intelligent is just beginning, and the 10 billion-dollar valuation of enterprises is still low.
The optimistic attitude of the head of the smart enterprise is clear, and the preservation of food over the winter is also another hand in preparing some enterprises for a potential crisis.
Which companies have received funding under the cooling?
Look closely, out of the 68 financing openings in October, 61 took place domestically, totaling about US$11.5 billion, compared to US$11.1 billion in September.
Financing of the Intelligent Industry Chain in October 2026
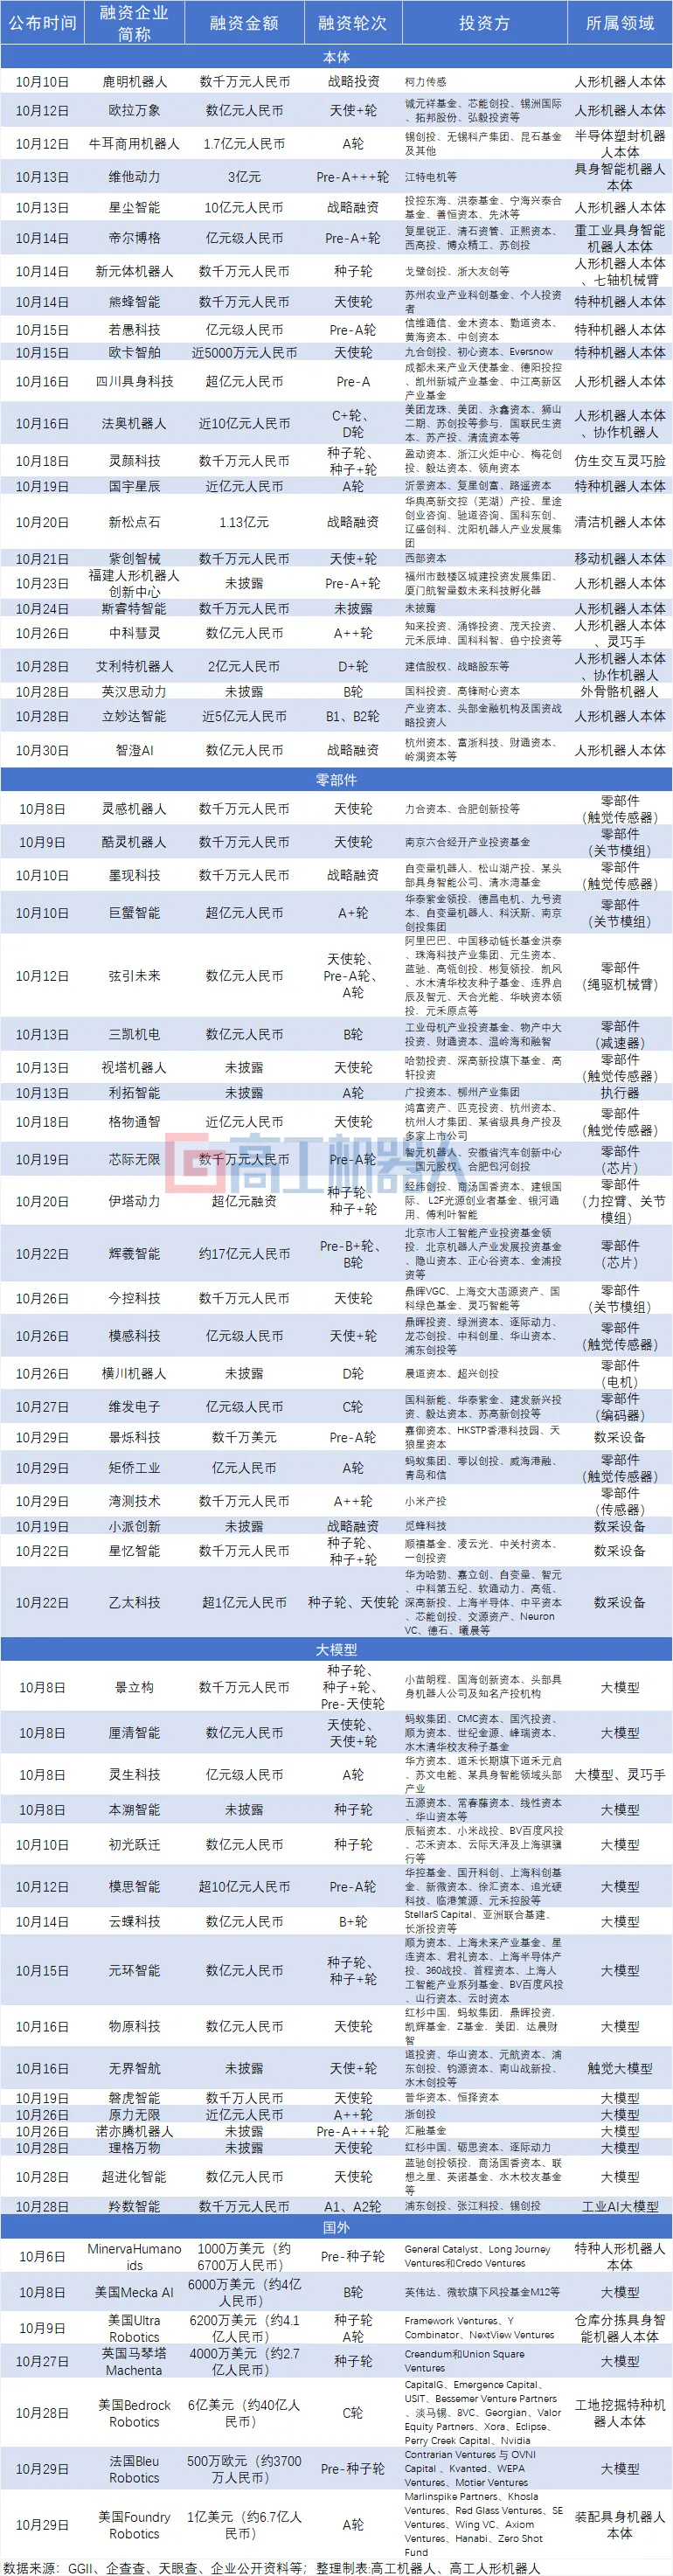
In terms of financing composition, SMBs and large model enterprises remain the most gold-absorbing sectors, together accounting for nearly 7 percent of total financing events and absorbing over 79 percent of total funding.
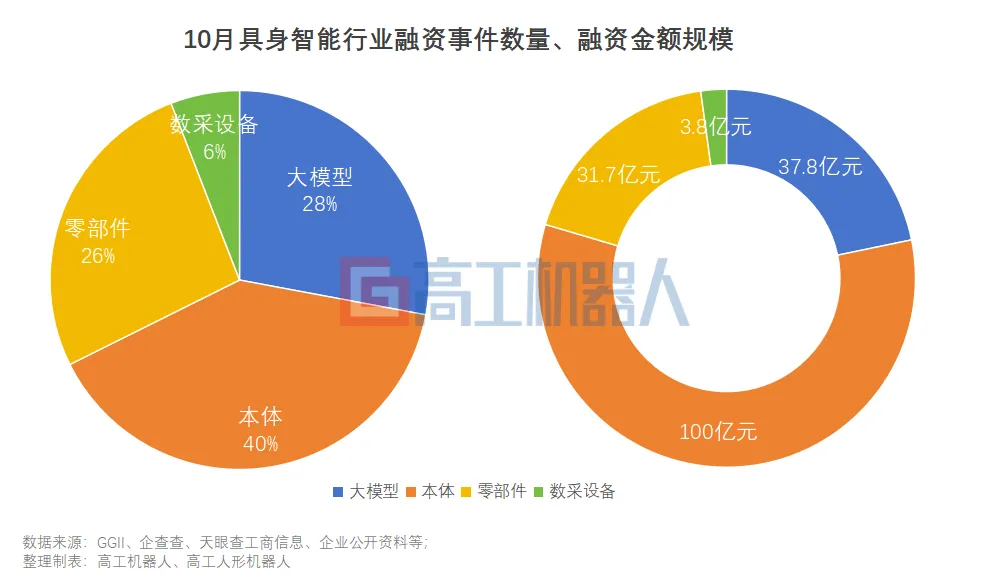
In October, 26 Furniture and Intelligent Robotics corporate officers announced that they had received funding covering human, quadruped, heavy-duty, specialty, and other fields.
In the field of parts, the financing of touch sensors has surpassed the funding of joint modules, drive systems such as motors, and has become the most preferred type of capital among the smart industrial chain components: inspiration robots, ink technology, VITAR robots, general intelligence, modem technology, matrix technology, and other touch sensors enterprises have completed a new round of financing.
Intelligent robot chips set the record for the most gold-absorbed in October, with Intelligent Pre-B+ and B rounds totaling 1.7 billion yuan topped the list in October.
To a large extent, today's physically intelligent robots have entered the mass production phase, and drive control devices such as motors, decelerators, encoders, joint modules have gradually matured, with capital focusing more on precision operations, tactile neural inputs to the world of physical AI perception, and computational chips.
In addition, it is worth noting that as an important part of the intelligent data evolution chain, companies such as VR Remote Control, Ego, UMI and others have also begun to invest separately.
For example, AT&T, which focuses on building physics-space intelligent engines, announced in October the completion of a billion-dollar seed round, angel round financing, and the shareholders' line-up is even more patient: Huawei, autonomous variables, Chiyo, the Chinese Fifth Dynasty, soft power, etc. Most of these investors have deployed humanoid robots, jointly invested in the consolidation of the same enterprise, and see the urgency of real manufacturers and model companies for high-quality reproducibility, AI-intelligible physical space data hunger and thirst.
The logic of smart investing has changed.
There's a classic saying in the stock market that psychological gambling is harder to beat than sitting in a dungeon.
Investors also have this FOMO (fear of missing out) sentiment that you don't throw, the next person is waiting for the throw, thexx institutions want to throw, this overwhelmingly limited decision-making strategy, afraid of breaking the psychology, which makes many investors get bogged down in smart projects.
The unreasonable narrative is gradually returning to a level playing field, and the richly irrigated holdings are beginning to be refined, with the focus of investors shifting from betting on a single-point capability of robotics enterprises to pursuing truly visible commercial land value and becoming an early staunch companion to individual disruptive technology routes.
Differentiation means that physical, model, data, simulation, and engineering capabilities must be integrated to further support the narrative that investors and markets expect.
The list of corporate smart robot companies that have been financing in October, can see that there are obvious trends and structural changes in investment finance logic and preferences:Engineering enterprises capable of having physically intelligent products that can land in real projects; new enterprises that are stepping into potentially disruptive technological routes; and enterprises that have mastered the capability of full-frame-model-data-closed circuit switching.
FARO robots offer solutions ranging from core components, power-controlled human arms to integrated ODM, products have been installed in shoe manufacturing, ship welding, CNC waste; FARO robots have gradually completed the deployment of AI infrastructure, optical communications, and optical module production lines in multiple assembly plants; FARO robots have also received more than 400 million shoe-making robot orders, and have made commercial progress in mining inspection and entertainment shows.
The other category of favored players is those who have mastered the full-circle closure capability of the body-model-data matrix in the body-smart industry. Know that each industry itself has a closed-circle. Such as Intelligent AI, Dust Intelligence, etc. Intelligent AI started with its own world model, subsequently developed an industrial-grade body-robot, general-purpose humanoid robot integrator, and has deployed benchmark scenarios such as the Intelligent Automobile Factory, National Power Network, to real-world anti-mammaculate world model capabilities; Star-Dust Intelligence formed the three core capabilities of the rope-driven matrix-Lumo Model-Astribot OS system, allowing intelligence and brain systems to replace hardware in data interaction.
The latter are companies that are on the path of innovation in technology - such as the big model, the recent explosion of RSI (Returning Intelligence to Self-Improvement) technology path, which wants AI to learn how to create a new generation of model generations, get rid of the traditional links of artificial data collection, training, labeling, deployment, reduce the bottleneck of physical AI's self-closing cognitive capabilities, and achieve a real hydrogen evolutionary leap. This is the main reason why companies such as RSI are at the heart of micro-intelligence, hyper-evolutionary intelligence, early-light leap.
At the end of the day, the rising cost of decision-making, the withdrawal of worries and the increasingly intelligent investment finance logic have shifted from the fear of missing the mark to the fear of making mistakes. Capital is no longer paying for a single longboard and PPT narrative, but is re-valued on the triple scale of scenario landscapes, full-circuit closures and disruptive technology routes.
I wrote it at the end.
A college-based entrepreneur who practices the Physical RSI technology pathway said that while the industry has had a lot of hot money pouring in in 2026, it is far from enough in terms of current technological maturity.
Another alarming signal was also released in 2026, not only in terms of the volume of potassium production falling in the local calendar year, but also in terms of the decentralized calendar year of potassium deployment and the decentralization of potassium in the smart industry. In a recent report published by the Institute of High-Industry Robotics Industry (IGII) and JIJT Retail Joint, Potassium Intelligent Progress Research Report 2026, it is predicted that over the next three years, more than 15 percent of domestic potassium-smart start-ups will face bankruptcy or mergers.
The signals of a month-on-month financing re-warm up are not a reflection of the cold-winter hypothesis, but rather a structural re-warm up, with funds not disappearing, but shifting from the pursuit of concepts to the ability to filter; the market has not given up physical intelligence, but has begun to re-pricing with orders, deployments and re-use.